
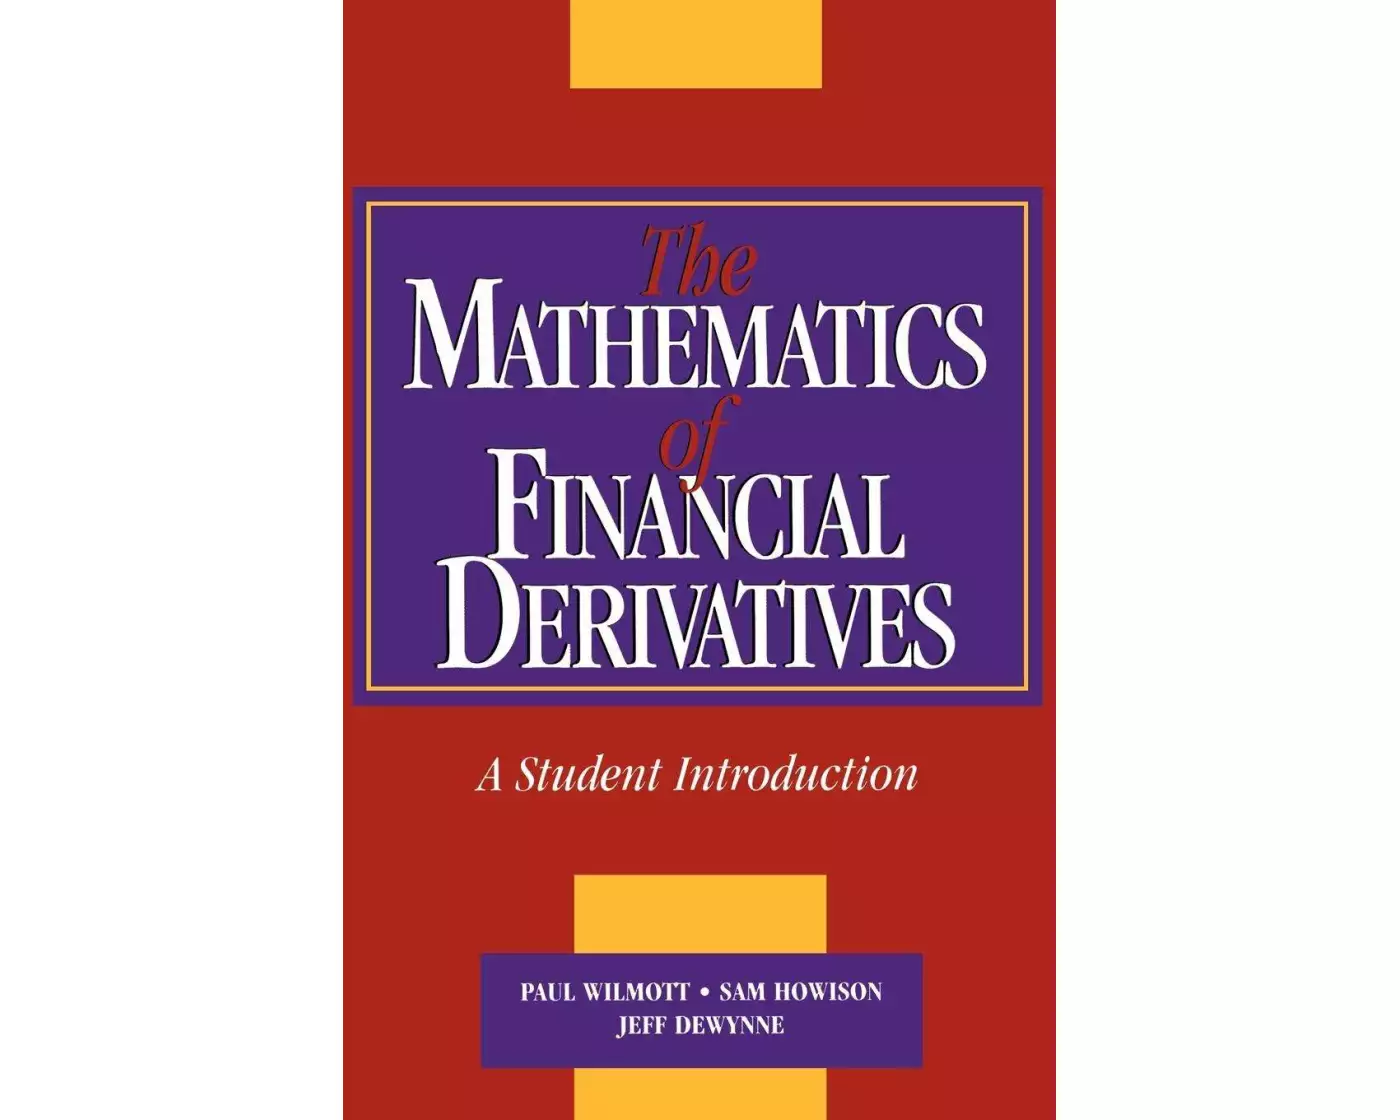
Erhältlich:Nicht auf LagerBuch (Softcover): Fachbuch
The Mathematics of Financial Derivatives
A Student Introduction
von Paul Wilmott, P. Wilmott, Susan Howson
- Unsere Artikel-Nr.
- 6Z974RN
Beschreibung
Finance is one of the fastest growing areas in the modern banking and corporate world. this, together with the sophistication of modern financial products, provides a rapidly growing impetus for new mathematical models and modern mathematical methods; the area is an expanding source for novel and relevant 'real-world' mathematics.
Spezifikationen
| Sprache | Englisch |
|---|---|
| Autor | Paul Wilmott, P. Wilmott, Susan Howson |
| Erscheinungsjahr | 1995 |
| Format | Buch (Softcover) |
| Anzahl Seiten | 336 |
Inhaltsverzeichnis
Part I. Basic Option Theory: 1. An introduction to options and markets; 2. Asset price random walks; 3. The Black-Scholes model; 4. Partial differential equations; 5. The Black-Scholes formulae; 6. Variations on the Black-Scholes model; 7. American options; Part II. Numerical Methods: 8. Finite-difference methods; 9. Methods for American options; 10. Binomial methods; Part III. Further Option Theory: 11. Exotic and path-dependent options; 12. Barrier options; 13. A unifying framework for path-dependent options; 14. Asian options; 15. Lookback options; 16. Options with transaction costs; Part IV. Interest Rate Derivative Products: 17. Interest rate derivatives; 18. Convertible bonds; Hints to selected exercises; Bibliography; Index.
Bewertungen
Produkt bewertenFür dieses Produkt liegt noch keine Bewertung vor. Wenn Sie es gekauft haben, teilen Sie gerne Ihre Erfahrung.
Zahlungsarten


Rechnung (Einzahlungsschein mit QR-Code), Twint, Kreditkarte, PostFinance, Apple, Google oder Samsung Pay.
Versand
Kostenlos: Schweiz & Liechtenstein
Rückgabe
30 Tage Rückgaberecht
Sie können das Produkt innerhalb von 30 Wochentagen ohne Angabe von Gründen zurücksenden, sofern es unbeschädigt und in der Originalverpackung ist.
Weitere Hinweise finden Sie in unseren AGB unter D.1.